Claim help for Garland homeowners
Water Damage Insurance Claim Garland TX: Steps And Rules
A water damage insurance claim Garland TX homeowners file goes well or badly in the first two days. What you photograph, what you keep and who you call first decide most of it. This guide sets out the steps and the Texas deadlines in plain words. We are not lawyers or adjusters, and your own policy always has the final say.
- What is usually covered
- Texas claim deadlines
- What to photograph and keep
- What to do if the claim is refused
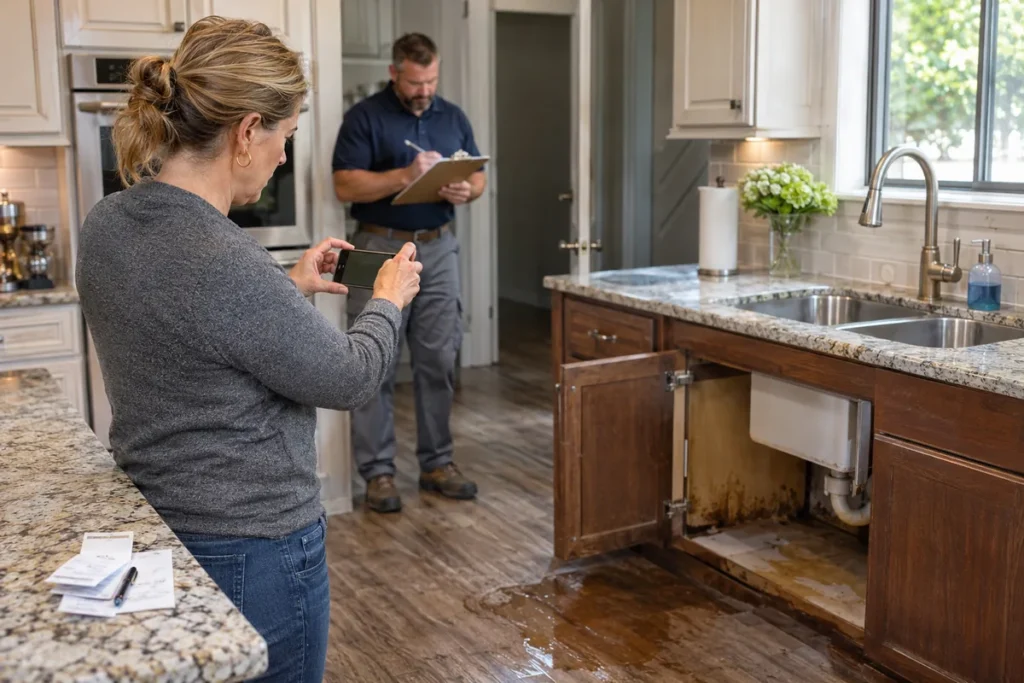
Do These Five Things First
These steps follow the advice the Texas Department of Insurance gives to policyholders.
- Stop the water.Shut the valve or the main. Your policy expects you to keep the damage from getting worse.
- Take photos and video of all damage.Do this before you move, dry or throw away anything.
- Make temporary repairs only.Mop up, cover a hole, move belongings. Leave permanent repairs until the insurer has seen the damage.
- Keep every receipt.Fans, tarps, a plumber’s call out, a hotel night. They can all be part of the claim.
- Report the claim.Call your agent or the insurer’s claim line the same day and write down your claim number.
Source: Texas Department of Insurance, Getting Your Insurance Claim Paid.
Water Damage Insurance Claim Garland TX: What Is Covered
The Texas Department of Insurance says most homeowners policies cover sudden and accidental water damage. The words sudden and accidental matter.
Usually Covered
- A pipe that bursts without warning
- A water heater or washing machine hose that fails
- Rain that gets in through storm damage to the roof
- Extra living costs if you cannot stay in the home
Usually Not Covered
- A slow leak that went on for weeks or months
- Flooding from rising water outside
- Damage from lack of upkeep
- Sewer or drain backup, unless you added that cover
Source: Texas Department of Insurance, Homeowners Insurance FAQ.
The Claim Process, Step By Step
- You file the claim.Give the date, the cause and a short list of what is damaged. Send your photos.
- The company asks questions.An adjuster visits or calls. You may be asked for receipts, a list of damaged items or a signed statement.
- The company decides.It tells you in writing whether it will pay all, part or none of the claim.
- You choose a contractor.You are free to pick who does the work. Get the scope in writing.
- You get paid.You pay your deductible. If you have a mortgage, the cheque may be made out to you and the lender together.
Source: Texas Department of Insurance, Getting Your Insurance Claim Paid.
Deadlines Your Insurer Must Meet In Texas
Texas law sets time limits on the insurer. Note the dates as you go.
| Stage | Time limit | What must happen |
|---|---|---|
| After you file | 15 business days | The company says it got your claim, starts its review and asks for what it needs |
| After you send what it asked for | 15 business days | The company tells you if it will pay. A refusal must give the reason in writing |
| If it needs longer | Up to 45 more days | The company must tell you why it needs more time |
| After it agrees to pay | 5 business days | The payment must be made |
After a weather catastrophe, the Texas Department of Insurance can extend these deadlines by 15 more days.
Source: Texas Department of Insurance, Getting Your Insurance Claim Paid.
What To Photograph And Keep
- The source: the split pipe, the failed hose, the hole in the roof
- Every wet room, wide shots and close ups
- The water line on walls and furniture
- Damaged belongings, with brand and model where you can
- The failed part itself, if the plumber can leave it with you
- Moisture readings and the drying log from the crew
- All receipts and all letters and emails from the insurer
- Notes of every phone call: date, name and what was said
The drying log is explained on our structural drying page.
Working With The Adjuster
The adjuster works for the insurance company. Be polite, be exact and stick to facts. Say what you saw and when you saw it. If you do not know the cause, say that you do not know. Do not guess.
Walk every wet room with the adjuster and point out damage that is easy to miss, such as baseboards, cabinet bases and the room on the other side of the wall. Ask for a copy of the adjuster’s written estimate, and compare it line by line with your contractor’s scope.
Flood Is A Separate Policy
Water that rises from outside, such as creek or street flooding, is not covered by a standard homeowners policy. It needs a flood policy, which most people buy through the National Flood Insurance Program.
A new flood policy normally takes effect only after a 30 day waiting period, so it has to be in place before the storm season. If you live near Duck Creek, check what you have now. More on this is on our flood cleanup page.
Sources: Texas Department of Insurance, Homeowners Insurance FAQ; FloodSmart, National Flood Insurance Program.
Choosing A Contractor Without Getting Burned
After a big storm, door to door offers arrive fast. The Texas Department of Insurance gives these tips.
- Ask friends and neighbours for references
- Do not sign a contract with blank spaces
- Do not pay in full up front
- Pay your deductible. A contractor who offers to waive it is a warning sign
Published prices that help you check a quote are in the Garland cost guide.
Source: Texas Department of Insurance, Getting Your Insurance Claim Paid.
If The Claim Is Refused Or Underpaid
- Get the reason in writing.The insurer must give it. Read which part of the policy it relies on.
- Answer with evidence.Send photos, the plumber’s report and the drying log that speak to that reason.
- Ask for a second look.Request a review by a supervisor or a second adjuster.
- Contact the state.The Texas Department of Insurance takes complaints and answers questions on 800-252-3439.
- Take advice.For a large claim, a licensed public adjuster or an attorney can review it.
Common Mistakes That Hurt A Claim
- Throwing out damaged items before they are photographed
- Starting permanent repairs before the adjuster has seen the damage
- Waiting days to report the leak
- Guessing at the cause when asked
- Not drying the house, then claiming for the mold that follows
- Losing receipts for emergency work
Areas We Cover In Garland
We take requests from every Garland ZIP code, 75040 to 75044.
Water Damage Insurance Claim Garland TX Questions
Should I call the insurer or a cleanup crew first?
Stop the water and take photos, then call both the same day. You do not need the insurer’s permission to remove water and prevent more damage.
How long does a water damage claim take in Texas?
The insurer has 15 business days to acknowledge the claim, 15 business days to decide once it has what it asked for, and 5 business days to pay after it agrees.
Will my premium go up if I claim?
It can. Ask your agent how a claim affects your policy before you file a small one that is close to your deductible.
Is mold covered?
It depends on the cause and on your policy limits. See our mold removal page and ask your agent.
Are you the company that does the work?
No. Fix Water Damage Garland TX is a referral service. We pass your details to an independent local restoration crew, and that crew quotes, does the work and bills you or your insurer directly. The full process is on our water damage restoration page.
Send Us The Details
Write what happened, where in Garland, and when it started. A short message is enough to get things moving.
Our message line is being connected. Please check this page again soon.